AML for real estate professionals
Screen buyers, sellers, and beneficial owners before closing. Detect shell-company purchases, monitor wires and cash deposits, and document suspicious property transactions — for brokerages, developers, and title companies subject to DNFBP and FinCEN rules.
Residential and commercial brokerages, developers, property managers, and title/escrow companies with AML obligations under FATF DNFBP rules, FinCEN residential real estate reporting, or local supervisor requirements.
Complii supports AML intake, screening, and monitoring — it is not an MLS, CRM, or title production system. Ingest transaction data via API or import.
Regulatory landscape
Typical obligations by jurisdiction and how Complii supports your program. Requirements vary — validate with your compliance counsel.
| Jurisdiction | Typical obligation | How Complii helps |
|---|---|---|
| United States | FinCEN residential real estate reporting and Geographic Targeting Orders | Buyer/seller CDD, UBO visibility, case evidence for reporting workflows |
| United States | BSA — suspicious activity in property transactions | TM on wires and cash, screening, SAR-ready case files |
| EU / UK | MLR / AMLD6 — estate agents and property professionals | Customer DD, corporate KYB, screening, risk-based monitoring |
| Colombia / LATAM | DNFBP rules and local FIU evidence for property transactions | Screening, document requirements, cases with transaction evidence |
| Global | FATF Recommendation 22 — real estate DNFBP due diligence | UBO graph, geographic risk, adverse media, audit trail |
Typical compliance workflow
Onboard
Collect buyer and seller KYC at offer or contract stage; capture entity structure for corporate purchasers.
Screen
Screen buyers, sellers, beneficial owners, and related parties against sanctions and PEP lists.
Monitor
Monitor wire transfers, earnest money, and cash components for structuring, rapid flips, and geographic risk.
Investigate
Document suspicious transactions in cases with deed, title, and payment evidence for filing or internal review.
Complii modules for this sector
Customers & onboarding
Buyer, seller, and agent profiles with transaction linkage.
Corporate Intelligence
Entity KYB, ownership graph, and UBO for LLC and trust purchases.
Screening & watchlists
Sanctions and PEP screening on all transaction parties.
Risk & policy
Property- and party-level risk scoring with company rules.
Transaction monitoring
Wire, cash, and velocity scenarios for property deals.
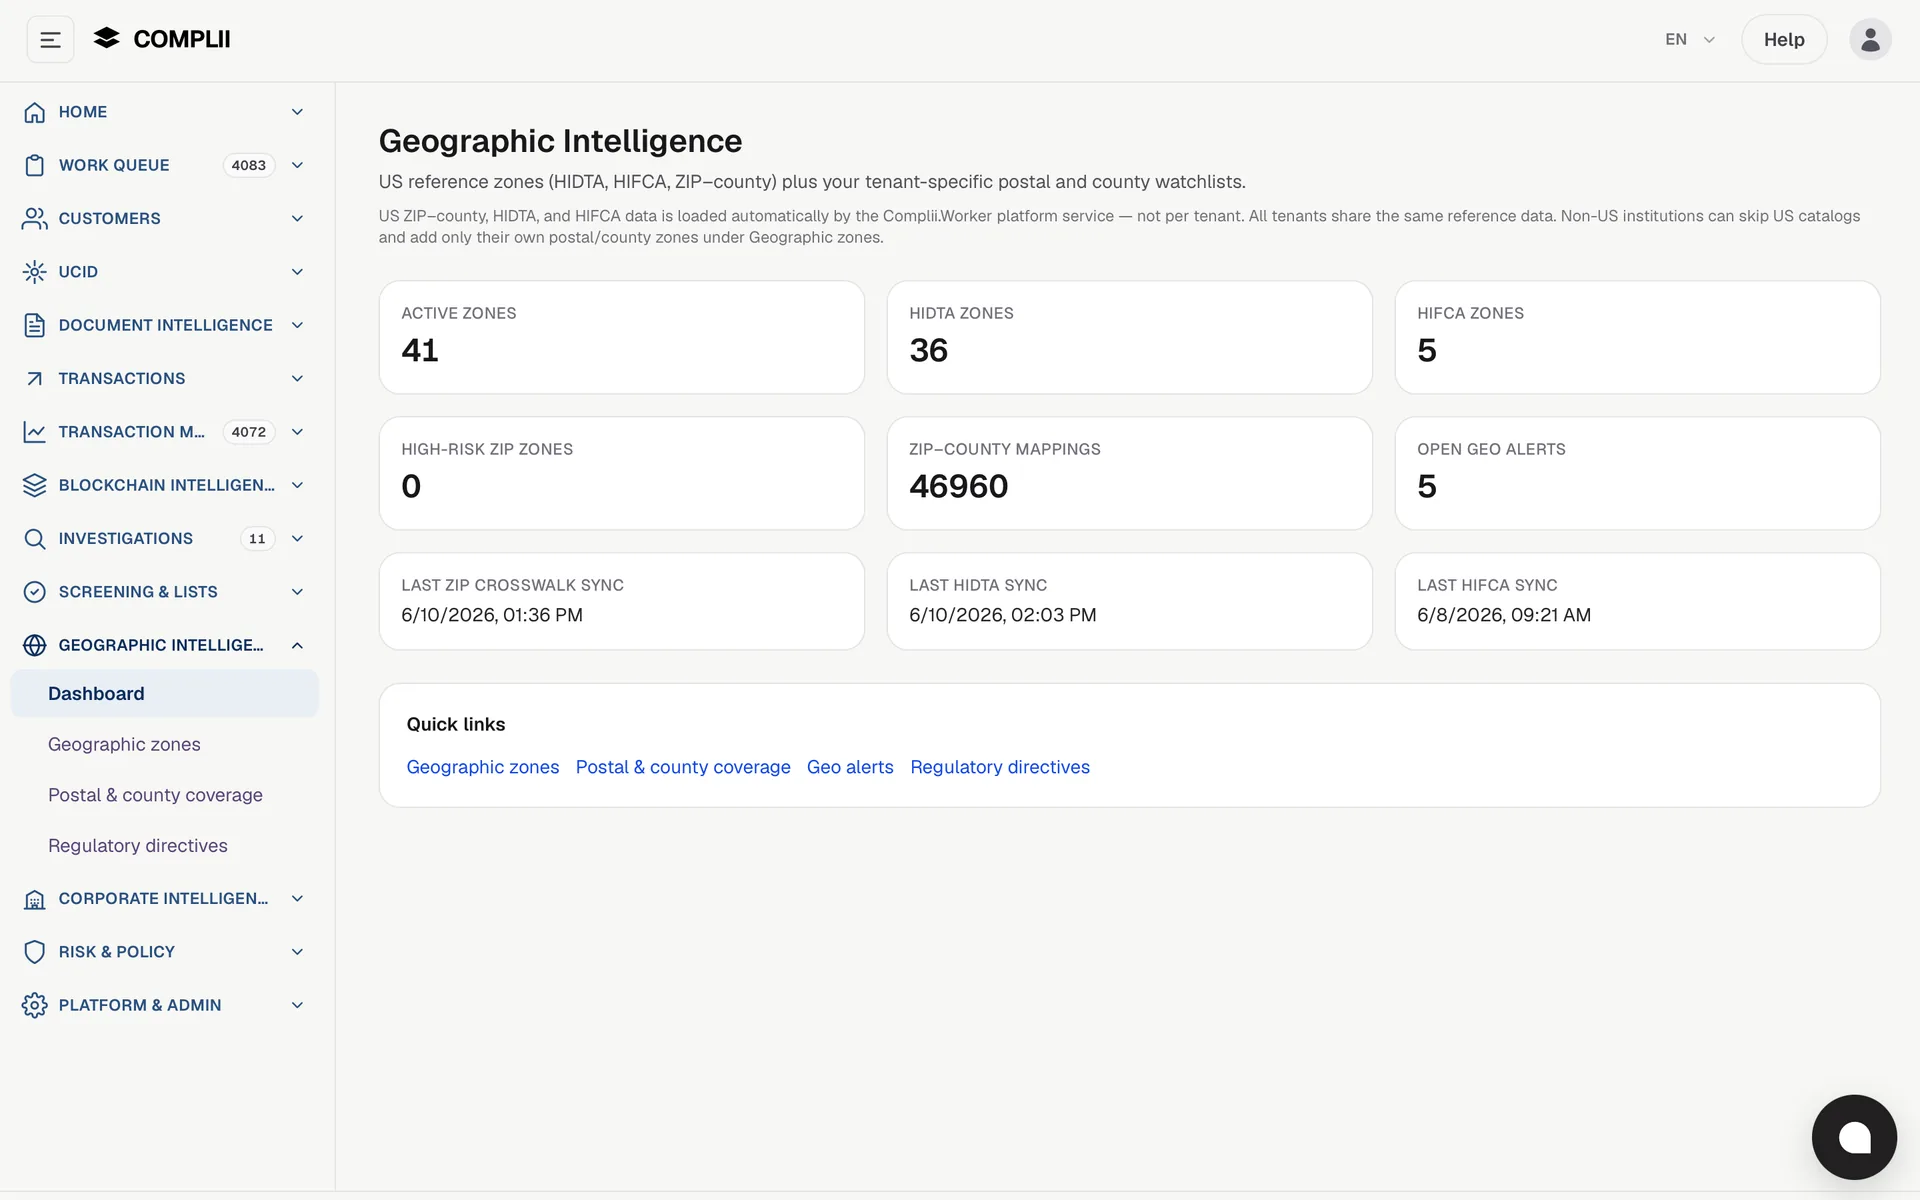
Geographic Intelligence
HIDTA/HIFCA zones and location-based transaction risk.
Document intelligence
Title, deed, and entity document validation.
Identity verification
Remote ID capture for out-of-state and international buyers.
Adverse media
Media checks on high-value buyers and developers.
Cases & investigations
Suspicious deal workflow with linked property and payment evidence.
Audit & compliance
Decision audit trail for regulator and firm review.
Without integrated AML tooling
- Buyer ID collected at closing with no screening integration
- Shell-company purchases accepted without UBO visibility
- All-cash deals flagged only after the fact
- Suspicious transactions documented in email, not cases
With Complii
- Screening and KYC at offer stage, before funds move
- Corporate Intelligence maps LLC and trust ownership chains
- TM alerts on cash components, wires, and rapid property flips
- Structured cases with deed, payment, and screening evidence
Ready to see Complii for your sector?
Build a quote with the modules your compliance program needs, or talk to our team about your regulatory context.